
In our last post, "The $1.37M Lie", we exposed how easy it is to manipulate financial backtests. We detailed how survivorship bias and unscrutinized historical data can make a random stock-picking monkey look like Warren Buffett. We committed to building our own sterilized 12-year testing environment (2014-2026) to find the truth about our proprietary 5-Pillar Stock DNA.
For the past few months, we went silent. We locked ourselves in the lab to stress-test our data pipelines. It was a grueling process of data debugging, identifying subtle leaks, and optimizing our machine learning algorithms.
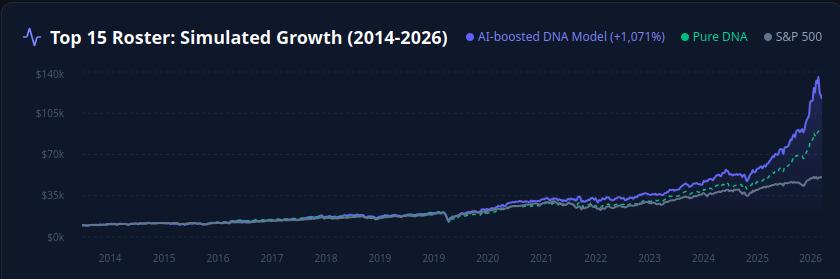
Today, we are sharing what we found on the other side of that process. We didn’t just validate our Stock DNA; we unlocked a +1,071% simulated return. And we did it by doing exactly the opposite of what the industry standard dictates.
The Illusion of Hindsight and the "Tech Trap"
Before we could even look at the returns, we had to ensure our data was bulletproof.
In the quantitative finance world, it is incredibly tempting to build a strategy that perfectly predicts the past. There is a common disclaimer floating around major financial platforms: "Backtesting can be adjusted until past returns seem optimal." This is the polite way of saying "curve-fitting"—tweaking your algorithm until it magically catches every past bull run.
For example, we could have easily cherry-picked the technology sector to inflate our numbers. If you simply bought and held the Technology Select Sector SPDR Fund (XLK) over the last decade, you would have generated an 11x return doing absolutely nothing. But that’s not an algorithm; that’s just riding a macroeconomic wave in hindsight.
To combat this, we implemented strict Point-in-Time (PIT) architecture to eliminate "Look-Ahead Bias." We ensured our algorithm only "sees" a financial metric (like an earnings report) well after it has been publicly filed and fully digested by the market, not the day the quarter ends. We also utilized rigorous parameter grid searches, but to avoid overfitting, we ran our best parameters multiple times and relied on the median results.
Our portfolio construction was brutally simple: At the start of each month, the algorithm buys the top 15 stocks signaling the highest structural strength. If a stock drops out of the top tier the next month, it gets replaced. No complex holding periods, just pure, monthly rebalancing based on fundamental health.
The Breakthrough: Redefining the Baseline
Despite our rigorous setup, the true breakthrough didn't come from a complex machine learning layer. It came from a fundamental shift in how we establish the baseline for our 5-Pillar Stock DNA.
Initially, we evaluated a company's DNA by comparing its metrics against a tight cluster of its direct competitors. It made sense on paper. However, we discovered that this micro-view often creates blind spots—sometimes an entire sub-sector is fundamentally sick, making a mediocre company look great by comparison.
Without giving away the "secret sauce" of our proprietary weighting, we can say that shifting our baseline away from immediate peers and restructuring how we measure a company against broader market mechanics changed everything.
The results were explosive. By zooming out and redefining the baseline, our Stock DNA suddenly became hyper-accurate at isolating true structural strength.
In fact, the results were so profound that if we stripped away all machine learning and built a portfolio purely based on our updated Stock DNA scores, the strategy generated over a +801% return over the 12-year period. Our Machine Learning layer simply added the final polish, pushing the final simulated return to +1,071%.
The Power of Pure Fundamental Rotation
We achieved these numbers using the most basic strategy imaginable: pure, unadulterated fundamental health rotation. No complex holding periods, no advanced charting—just buying the highest DNA scores every month.
The Vision: Your Strategy, Powered by EquitAI DNA
This realization sparked our ultimate vision for EquitAI. If our pure DNA scores can drive a +801% baseline using a brutally simple rotation, imagine what happens when a seasoned trader or quantitative analyst pairs that DNA with their own macro-thesis, technical indicators, or advanced portfolio management strategies.
That is why we launched the EquitAI Roster—a transparent, monthly showcase of our top 15 algorithmically driven opportunities. But we aren't stopping there.
We are currently laying the groundwork for a comprehensive Backtesting Platform. Soon, you won't just consume our Roster; you will be able to utilize our 5-Pillar Stock DNA as the ultimate fundamental filter for your own custom algorithms. We are building the infrastructure for you to compound our research with your expertise.
We survived the lab. The DNA is proven. Now, it's time to put it to work.
Explore the Monthly EquitAI Roster today and see the power of quantified structural health for yourself. Explore the Monthly EquitAI Roster